
Large Loan Valuation remains one of the biggest challenges for project finance, commercial real estate and fund financing portfolios.
For low-default, non-granular loan portfolios such as project finance, commercial real estate and fund financings, historical data are often scarce, even when enriched with datasets such as Global Credit Data (GCD). As a result, banks and institutional investors rely on bottom-up borrower-level financial models rather than the statistical top-down approaches commonly used for granular retail or SME portfolios. This paper establishes a methodology for reconciling forward-looking structural valuations with observed historical default rates, cure rates and recovery outcomes.
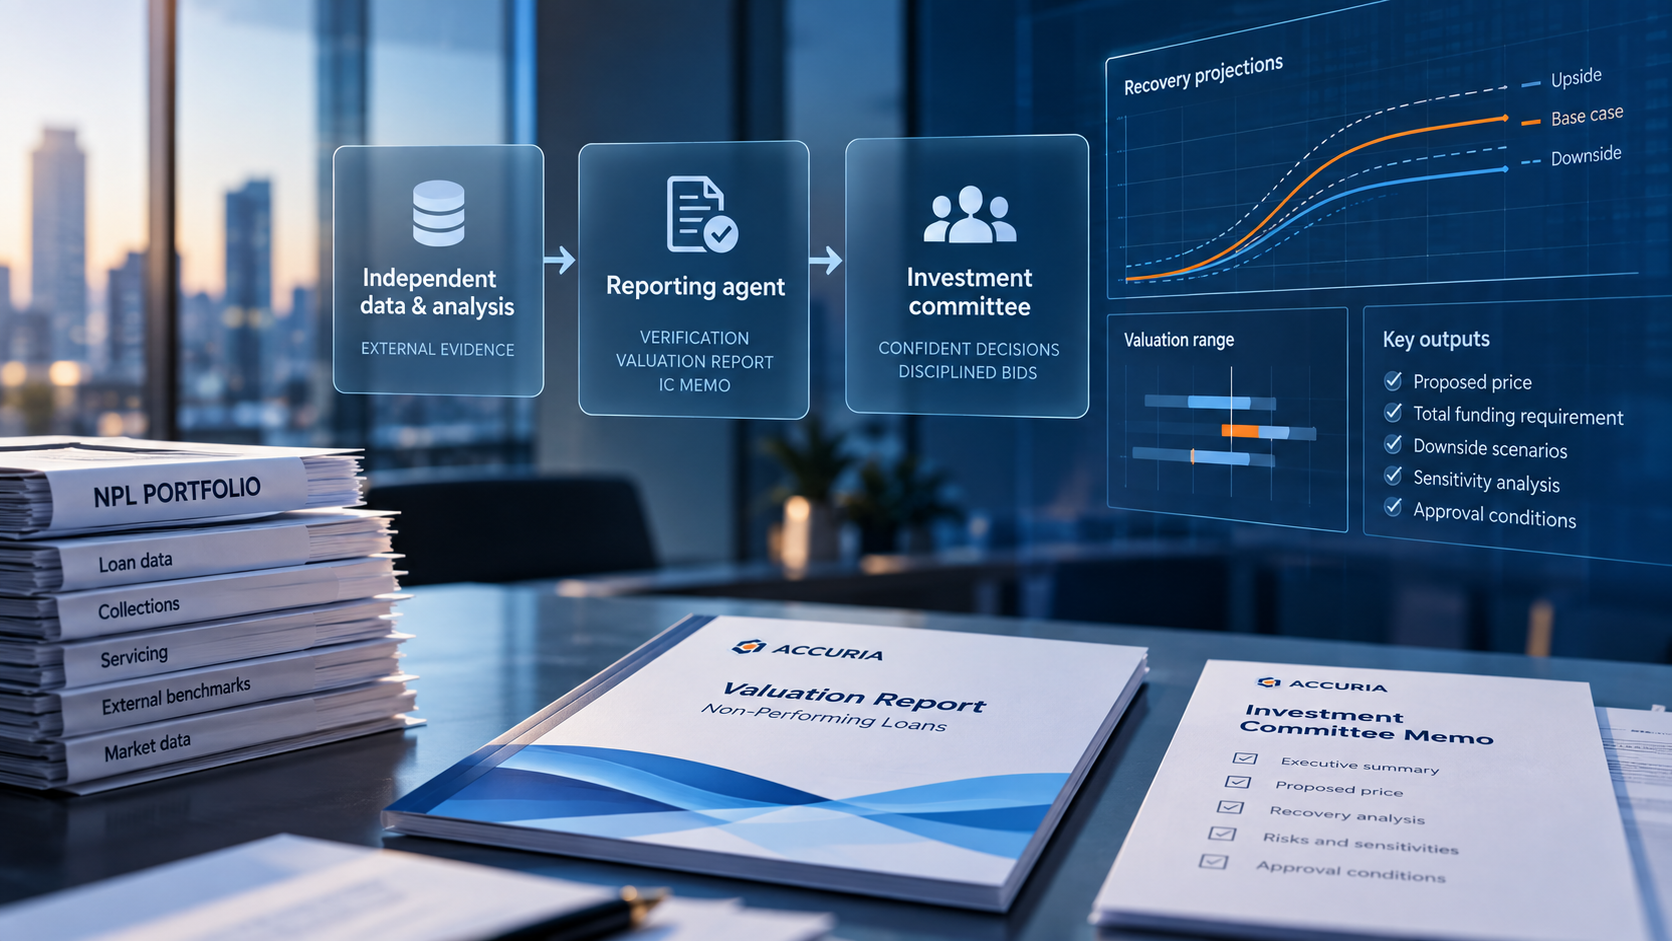
Drawing on the Merton structural credit model, Bayesian calibration techniques and more than 350,000 non-retail defaulted loan observations from GCD, the paper presents a seven-step valuation algorithm integrated with agentic AI. The framework produces consistent outputs for IFRS 9 Expected Credit Loss (ECL), IRB regulatory capital and IFRS 13 fair value. Worked examples covering German wind park project finance and Italian hotel commercial real estate demonstrate how the methodology performs in practice.
Reliable Large Loan Valuation depends on robust historical data and statistically sound methodologies. By combining Global Credit Data, historical recoveries, Bayesian calibration and agentic AI, financial institutions can improve valuation accuracy while supporting regulatory compliance and more consistent investment decisions. The framework enables banks and investors to produce transparent, repeatable and fully auditable valuations across complex lending portfolios.
Read the full article to learn how Global Credit Data and historical recoveries improve large loan valuation: Valuation of Large Loans Anchored to Historical Recoveries